
The Week in 30 Seconds
- [MACRO] Fed rate hike delivered. 12-0 vote, +25bp to 3.75-4.00% — first hike since July 2023. Dot plot: 16 of 18 see one more this year, median 2026 rate 4.10%. 2Y yield ripped past 4.6%.
- [MACRO] BOJ hikes to 1.25%. 31-year high on a 7-2 vote — fastest cadence since 1990. But yen weakened past 157 as guidance disappointed. USD-JPY carry still wide vs Fed.
- [TECH/AI] Nvidia Rubin NVL72 +7.2x over Blackwell at 150 TPS. Bigger step-up than the last generation. Perplexity local agent shipped on RTX. Salesforce Koa launched at Dreamforce. Second consecutive big AI capex signal.
- [EARNINGS] FedEx Q1 FY27 crushes. EPS $3.83 vs $3.71, revenue $22.2B vs $21.7B. FY27 revenue guide to 4-6% (vs Street 1.2%). Volumes stronger than the Fed rate hike week narrative suggests.
- [SG/MY] STI ~5,656 (-0.6%), KLCI under pressure, ringgit weak. Rate-hike shock pre-priced. Playbook: overweight banks + AI chain + DC REITs + upstream + logistics; underweight long-duration REITs + airlines + palm.
1. Fed rate hike: The Fed Rate Hike Everyone Priced Actually Landed

Meanwhile, the Fed rate hike arrived on Wednesday September 17 exactly as the market had priced. The FOMC voted 12-0 to raise the federal funds target range by 25 basis points to 3.75-4.00% — the first Fed rate hike since July 2023 and the opening move of the Kevin Warsh chairmanship. Warsh, at the post-decision press conference, framed the vote in unusually direct language: inflation has been ‘too high, for too long’ and the Committee is committed to a ‘timelier return’ to the 2% objective. The updated Summary of Economic Projections was the real hawkish signal — 16 of 18 participants now expect at least one more 25bp hike before year end, with the median 2026 terminal rate at 4.10% and the 2027 median holding at 4.10% before drifting to a low-4% path. The 2Y Treasury yield ripped past 4.6% for the first time since July 2024 and the curve bear-flattened. The S&P 500 finished the week down just 0.1% — the hike was already in the tape.
For Singapore and Malaysia investors, the Fed rate hike locks in the positioning frame for the rest of the quarter. The quality Singapore banks (DBS, OCBC, UOB) keep their net-interest-margin tailwind through year-end because a 4.10% year-end dot means SOR/SORA stays elevated — the NIM story that supported bank earnings through 2024 gets a second wind. The rate-sensitive REIT complex (CICT, MPACT, Frasers Centrepoint Trust, Keppel DC REIT, Digital Core REIT) now has to trade against a 2Y yield that will not compress meaningfully until the dot plot itself softens — expect the yield-versus-risk-free spread to stay tight into Q4. The stronger-dollar bias implied by 4.10% dots also renews pressure on the ringgit, adding an FX translation drag for KLCI-listed names and pushing Bank Negara toward a hold at the November MPC. The most important cross-current: the Oracle AI Cloud print from last week and the Nvidia Rubin benchmarks this week are structural signals that dominate this 25bp Fed rate hike for a multi-year AI capex thesis — UMS Holdings, AEM, Frencken, Aztech Global, Inari Amertron, Venture Corporation, Vitrox, Grand Venture Technology, and the two Singapore DC REITs stay on the overweight list despite the near-term rate noise.
2. BOJ 1.25%: Fastest Hike Cadence Since 1990 Fails to Buoy the Yen
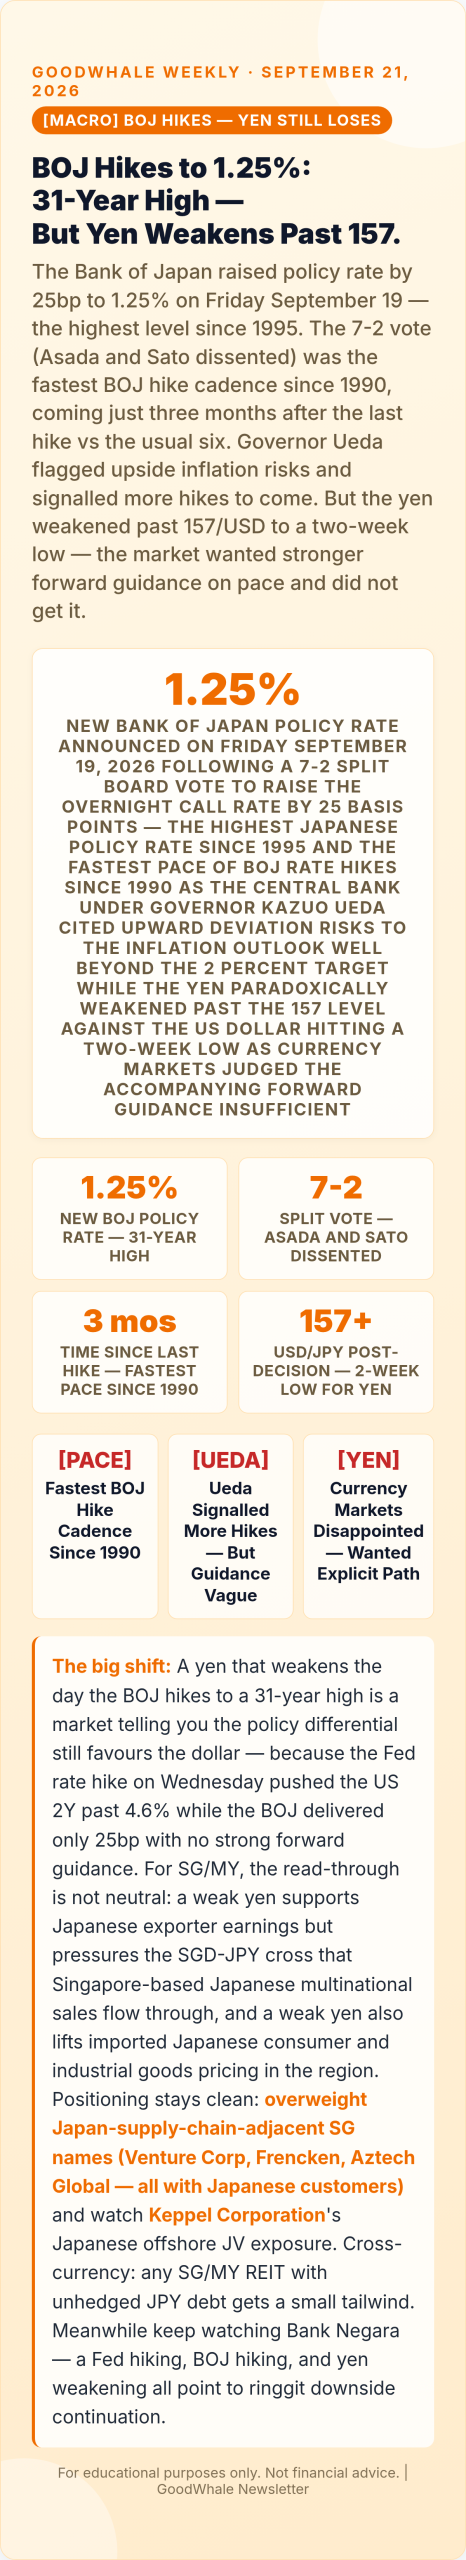
Notably, the Bank of Japan delivered its own hike on Friday September 19, closing the central-bank triple-header of the week. The BOJ Policy Board voted 7-2 to raise the overnight call rate by 25 basis points to 1.25% — the highest Japanese policy rate since 1995. Governor Kazuo Ueda cited upward deviation risks to the inflation outlook beyond the 2% target and signalled that additional hikes would follow, though he offered no explicit calendar. The move came just three months after the previous hike, which is the fastest BOJ tightening cadence since 1990 when Japan was in a very different economic era. Board members Asada and Sato dissented, arguing for a hold. Currency markets, curiously, punished the yen: USD/JPY pushed past 157 for a two-week low, as traders judged the accompanying forward guidance to be too soft against the 25bp Fed rate hike delivered two days earlier.
For Singapore and Malaysia investors, the BOJ move interacts with the Fed rate hike in a way that keeps the policy-differential trade alive. With the US 2Y at 4.6% versus the BOJ at 1.25%, the carry math still favours the dollar even after two hikes in the same week — that is why the yen weakened. This has three concrete regional implications. First, the Japan supply-chain names in Singapore — Venture Corporation, Frencken Group, Aztech Global — retain earnings tailwind from the weak-yen customer base but face a translation drag on any JPY-denominated revenue. Second, the SGD-JPY cross keeps trending, which puts pressure on Singapore-based Japanese multinational sales flow. Third, the ringgit — already weak against the SGD — is squeezed further because a stronger dollar leg from the Fed side keeps MYR downside pressure alive. Bank Negara’s November MPC now looks like a clear hold. On the equity side, Keppel Corporation keeps its Japanese offshore JV exposure and any SG or MY REIT with unhedged JPY debt gets a small tailwind on the FX translation. Watch for BOJ verbal intervention if USD/JPY approaches 160 — that is the level at which the Ministry of Finance historically steps in.
3. Nvidia Rubin +7.2x: The Second Big AI Capex Signal in Two Weeks
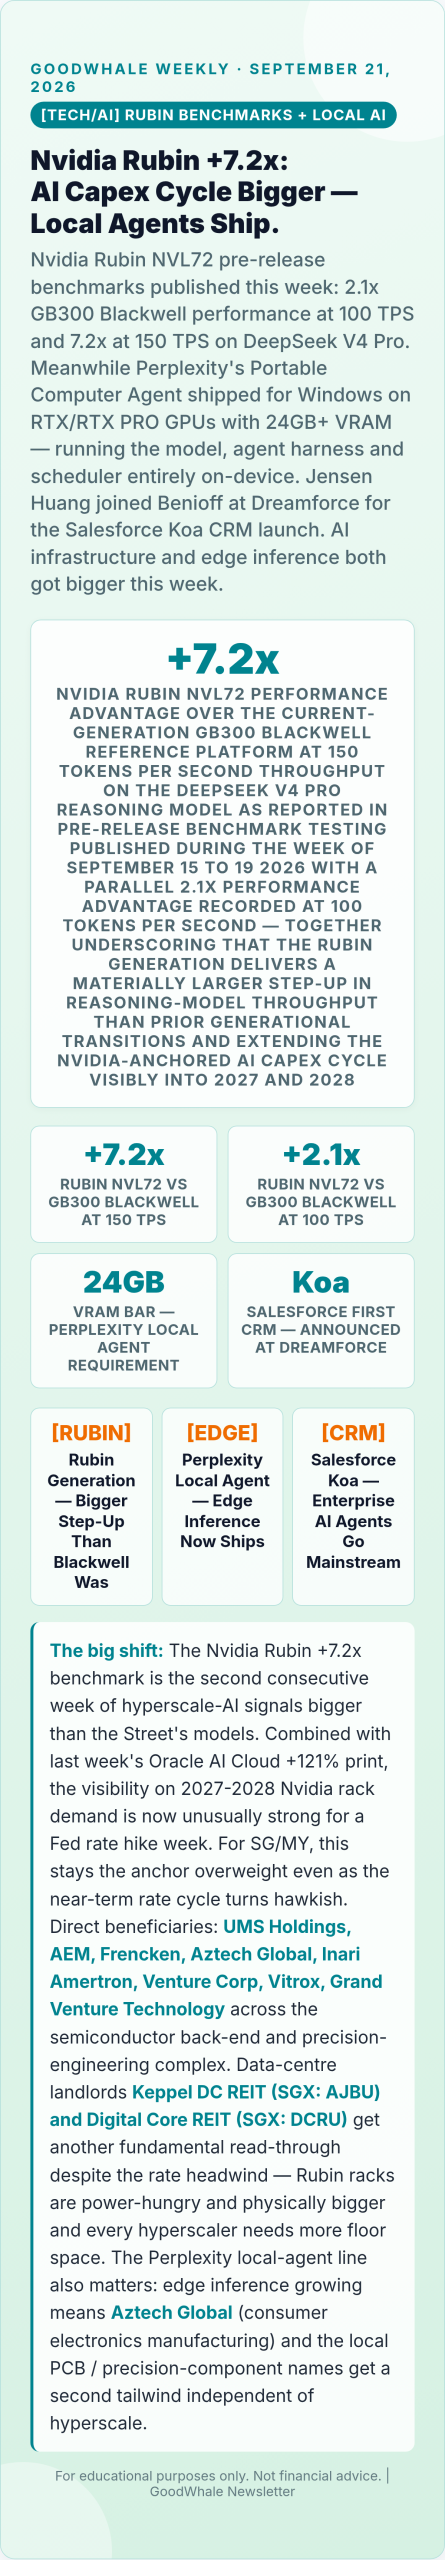
However, the AI capex story got a second oversized signal this week, one week after the Oracle AI Cloud print. Nvidia’s pre-release benchmark disclosures on the Rubin NVL72 platform, running the DeepSeek V4 Pro reasoning workload, showed a 7.2x performance advantage over the current GB300 Blackwell reference at 150 tokens per second and a 2.1x advantage at 100 tokens per second. That is a bigger generational step-up than Blackwell was over Hopper, and it lands in a market that just watched Oracle raise FY27 guidance to $90B in revenue on OCI +121% growth. Together, the two prints extend Nvidia-anchored AI capex visibility firmly into 2027 and 2028 — a 25bp Fed rate hike does not break that arithmetic. On the edge side, Perplexity’s Portable Computer Agent shipped on Windows for RTX and RTX PRO GPUs with 24GB+ VRAM, running the model, harness, orchestrator and scheduler entirely on-device via a locally optimised Qwen model — the first meaningful edge-agent shipment from a major LLM lab. And at Dreamforce, Jensen Huang joined Marc Benioff on stage for the announcement of Salesforce Koa, Salesforce’s first CRM built around agent primitives.
For Singapore and Malaysia investors, the Rubin benchmark set is the confirmation that the AI supply chain thesis dominates the near-term Fed rate hike noise. UMS Holdings, AEM, Frencken, Aztech Global, Inari Amertron, Venture Corporation, Vitrox, and Grand Venture Technology across the semiconductor back-end and precision-engineering complex all sit downstream of the physical build-out of Rubin racks — the packaging, the test, the precision mechanical parts, the thermal-management components — and the visible 2027-2028 capex extension means the earnings trajectory of these names does not depend on the Fed pivoting. The two Singapore data-centre REITs — Keppel DC REIT (SGX: AJBU) and Digital Core REIT (SGX: DCRU) — remain the pure-play landlord bet on the physical AI infrastructure that Rubin racks will inhabit; Rubin racks are power-hungry and physically bigger than Blackwell racks, which specifically favours the last remaining large-power hyperscale zones in Singapore and Johor. The Perplexity local-agent line adds a second, independent tailwind: edge inference growing at scale is directly positive for Aztech Global (consumer electronics assembly) and the local PCB, precision-component, and connector names, because RTX 40/50-series volumes into premium notebooks and desktops now have a real usage-driven demand pull rather than just a spec-race demand pull.
4. FedEx Q1 FY27: Volumes Say the Economy Is Warmer Than the Curve
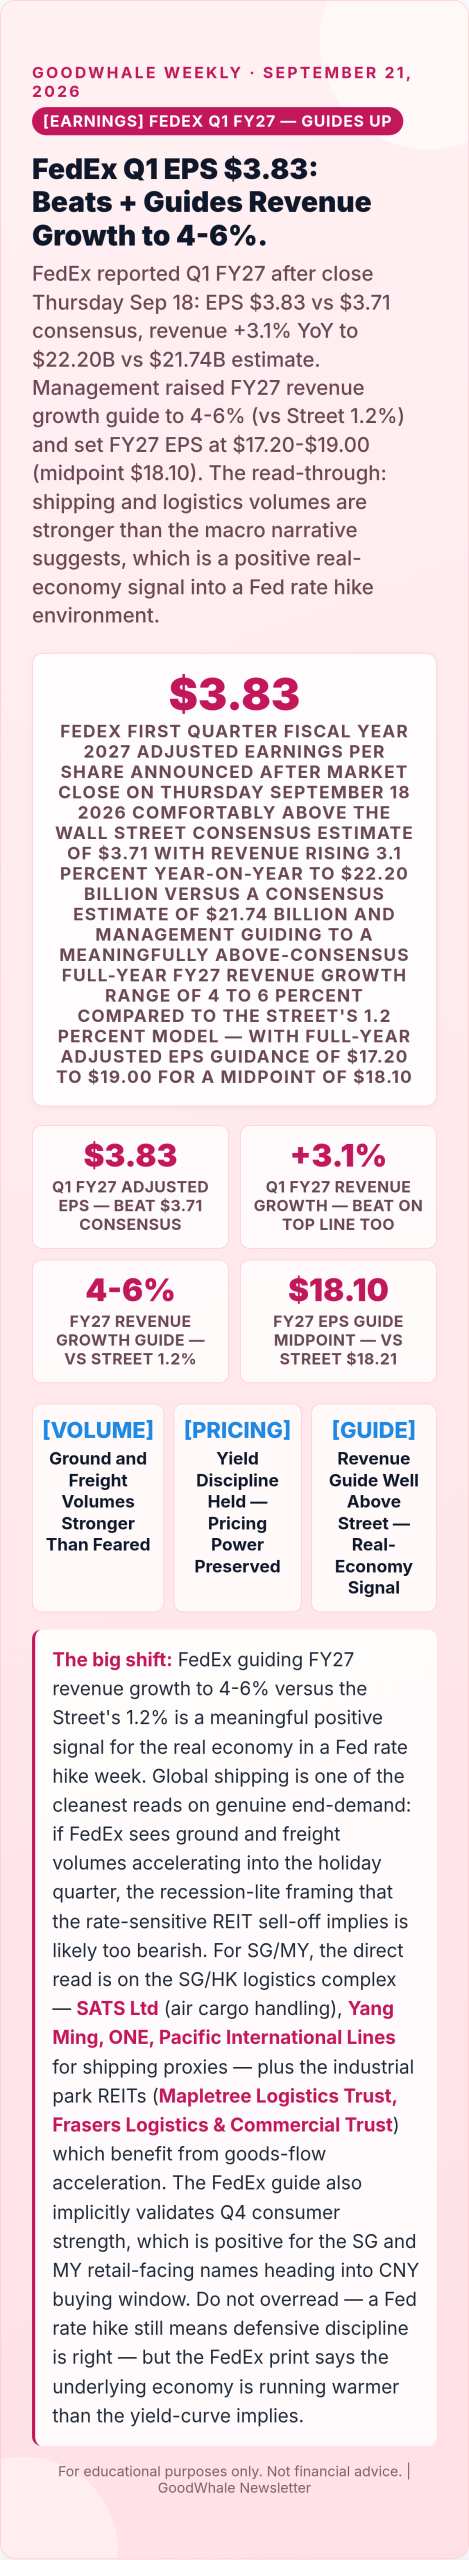
Additionally, fedEx delivered a strong Q1 FY27 print after close on Thursday September 18, and the read-through matters more than the number. Adjusted EPS came in at $3.83 versus the $3.71 consensus, with revenue rising 3.1% year-on-year to $22.20 billion against a $21.74 billion estimate. Both ground and freight volumes were stronger than the sell-side had modelled, and yield discipline held — pricing power was preserved through the print. Most importantly, management raised FY27 revenue growth guidance to a 4-6% range against the Street’s 1.2% consensus model, and set FY27 adjusted EPS guidance at $17.20 to $19.00 for a midpoint of $18.10 versus consensus $18.21. That combination — big revenue raise, EPS midpoint at consensus — is a volume-driven, mix-supportive print: FedEx sees the physical goods economy running faster than the Street’s forecast, even in a week where the Fed rate hike explicitly signalled higher-for-longer.
For Singapore and Malaysia investors, the FedEx print is a useful cross-check against the rate-sensitive selloff narrative. Global shipping is one of the cleanest real-time reads on end-demand: if ground and freight volumes are accelerating into the holiday quarter, the framing that a 25bp Fed rate hike ends near-term growth is almost certainly too bearish. Direct regional read-throughs sit in the SG and MY logistics complex. SATS Limited — the air cargo handling name at Changi — benefits directly from any global-freight acceleration, and the CNY buying window into SEA gets a volume tailwind from stronger US-consumer momentum implied by the FedEx guide. The industrial park and warehouse REITs — Mapletree Logistics Trust and Frasers Logistics & Commercial Trust — sit downstream of goods-flow acceleration through the Singapore hub, and while the rate headwind is real, the fundamental occupancy story is more constructive than the yield-versus-2Y compression math suggests. On the shipping side, the container-liner proxies through the region (Yang Ming, ONE, Pacific International Lines) also benefit from volume mix. Do not overrotate — a Fed rate hike still means defensive discipline is right, and the REIT complex still has a compressed distribution-yield-vs-risk-free spread — but the FedEx real-economy signal argues against panic-selling the goods-flow chain into the September 17 hawkishness.
| Signal | Fed | BOJ | Rubin/AI | FedEx / SG-MY |
|---|---|---|---|---|
| Headline Number | 3.75-4.00% | 1.25% | Rubin +7.2x | FedEx $3.83 / STI 5,656 |
| Market Reaction | 2Y at 4.6% | Yen 157+ | AI names firm | STI -0.6% weekly |
| Direction Signal | One more hike ’26 | More hikes ahead | Capex to ’28 | Real-econ warm |
| SG/MY Read | DBS/OCBC/UOB | MYR pressure | UMS/AEM/DC REITs | SATS/MLT |
| Verdict | Priced, Defensive | Diff Still Wide | Structural Bull | Overweight |
5. STI Post-FOMC: The Fed Rate Hike Is Priced, the Playbook Is Clear

On the other hand, the Straits Times Index absorbed a rare central-bank triple-header — Fed hike Wednesday, BOE hold Tuesday, BOJ hike Friday — with a controlled weekly pullback: from a prior-week close near 5,689 to approximately 5,656 by Friday close, for a weekly change of around -0.6%. The S&P 500 finished the same week down just 0.1% — the Fed rate hike was fully priced into the tape by the time Warsh took the podium. In Singapore, the composition of the pullback matters more than the headline: the rate-sensitive REITs and long-duration bond proxies took most of the weight while the chip and precision-engineering names held firm on the continued Nvidia Rubin and Oracle AI Cloud fundamental read-through. In Malaysia, the KLCI stayed under pressure as the ringgit continued to weaken against the SGD and the dollar — the combination of a hiking Fed and a hiking BOJ keeps the MYR downside pressure alive, and Bank Negara now looks certain to hold at the November MPC.
For Singapore and Malaysia investors, the positioning frame for the next four to six weeks is unusually clean after this Fed rate hike. On the overweight side: the Singapore banks (DBS, OCBC, UOB) keep the NIM tailwind through year-end because the 4.10% dot plot anchors elevated SORA/SOR; the AI supply chain (UMS Holdings, AEM, Frencken, Aztech Global, Inari Amertron, Venture Corporation, Vitrox, Grand Venture Technology) stays the highest-conviction structural overweight on the Rubin + Oracle capex extension into 2028; the two Singapore data-centre REITs (Keppel DC REIT SGX: AJBU, Digital Core REIT SGX: DCRU) remain the pure-play AI-infrastructure landlords despite the near-term rate headwind; SG/MY upstream (Petronas Chemicals 5183.KL, Dialog Group, Yinson Holdings, MISC Berhad, Rex International) keep the sector-rotation bull thesis alive at the $95-105 Brent regime that persists through the Iran-Gulf de-escalation channel; and the logistics beneficiaries (SATS Ltd, Mapletree Logistics Trust, Frasers Logistics & Commercial Trust) pick up a positive read from the FedEx +4-6% FY27 revenue guide. On the underweight side: long-duration bond-proxy REITs (CICT, MPACT, Frasers Centrepoint Trust) on any bounce as the yield-versus-risk-free compression persists; regional airlines (SIA, AirAsia 5099.KL, Capital A) on the sustained jet-fuel headwind; and palm oil pure-plays until the MPOB inventory print stabilises. The takeaway: the Fed rate hike is behind us, the shock is priced, and the AI capex signal is what dominates the trade for the rest of the quarter.
What I’m Watching Next Week
Key data and events — September 22 to 26
- Tue 23 Sep — US S&P Global flash PMIs. First real-time read on how business activity handled the Fed rate hike.
- Wed 24 Sep — US new home sales. Rate-sensitive housing pulse post-hike.
- Thu 25 Sep — US Q2 GDP final revision + jobless claims + Micron earnings. Micron is the crucial memory read for the AI supply chain thesis.
- Fri 26 Sep — US PCE inflation (August) + Michigan sentiment. PCE is the Fed’s preferred gauge — it must show softening or the next hike gets locked in.
- Local names — STI chip complex on Rubin read-through (UMS/AEM/Frencken/Venture/Vitrox/Aztech); Keppel DC + Digital Core REIT on the AI-infra thematic; DBS/OCBC/UOB on NIM tailwind; SIA/AirAsia headwind on jet fuel; Petronas Chemicals/Dialog/Yinson on the oil regime.
Bottom Line
The Fed rate hike everyone priced actually landed this week — 25 basis points to 3.75-4.00% on a 12-0 vote, first Fed rate hike in three years, and the opening move of the Kevin Warsh chairmanship. The dot plot showed 16 of 18 officials expecting one more hike before year-end with the median 2026 rate at 4.10%, and the 2-year Treasury yield ripped through 4.6% for the first time since July 2024. Two days later the Bank of Japan hiked to a 31-year high 1.25% but the yen still weakened past 157 to a two-week low because the policy differential with the Fed is still wide — the market wanted stronger BOJ forward guidance and did not get it. Bank of England held at 3.75% with a 6-3 vote where the three dissenters wanted to hike. And yet the S&P closed the week down just 0.1% and the STI closed near 5,656 for a -0.6% weekly pullback — the entire hawkish shock was pre-priced into the tape. Meanwhile the structural AI capex story got its second oversized signal in two weeks: Nvidia’s Rubin NVL72 posted 7.2x performance over GB300 Blackwell at 150 tokens per second on DeepSeek V4 Pro, extending the visibility on Nvidia rack demand firmly into 2027 and 2028; Perplexity shipped its Portable Computer Agent locally on RTX GPUs; and Salesforce launched Koa, its first agent-native CRM, with Jensen Huang on stage at Dreamforce. FedEx crushed Q1 FY27 with EPS $3.83 versus $3.71 consensus and — crucially — raised full-year revenue growth guidance to 4-6% against the Street’s 1.2% model, which is a real-economy signal that the physical goods flow is running warmer than the yield curve is pricing. For Singapore and Malaysia investors the post-FOMC playbook is unusually clean: overweight the Singapore banks (DBS, OCBC, UOB) on renewed NIM tailwind; overweight the AI supply chain (UMS Holdings, AEM, Frencken, Aztech Global, Inari Amertron, Venture Corporation, Vitrox, Grand Venture Technology) on the Rubin + Oracle capex extension; overweight the two Singapore data-centre REITs (Keppel DC REIT, Digital Core REIT) as the pure-play AI-infrastructure landlords despite the rate headwind; overweight SG/MY upstream (Petronas Chemicals, Dialog Group, Yinson Holdings, MISC Berhad) on the $95-105 Brent regime; overweight the logistics beneficiaries (SATS, Mapletree Logistics Trust, Frasers Logistics & Commercial Trust) on the FedEx real-economy signal. Underweight long-duration bond-proxy REITs (CICT, MPACT, Frasers Centrepoint Trust) on any bounce, underweight regional airlines (SIA, AirAsia, Capital A) on the jet-fuel headwind, and underweight palm oil pure-plays until the MPOB inventory print stabilises. The Fed rate hike is now history and the AI capex signal is what dominates the multi-quarter trade — position with discipline, but do not exit the structural bull leg because a 25bp move never breaks a 2028 capex cycle.
For educational purposes only. Not financial advice. Always do your own research. Catch up on last week’s issue: GoodWhale Weekly: Nvidia earnings 2026 Beats, Warsh Turns Hawkish, Everything Reprises.





[…] Previous […]